Pension Contributions Through the Company: One of the Most Valuable Director Planning Tools
For many owner-managed companies, pension planning is considered only after salary and dividends have been decided.
Understanding company pension contributions for directors is essential to maximise tax efficiency and retirement planning.
That can be a mistake. 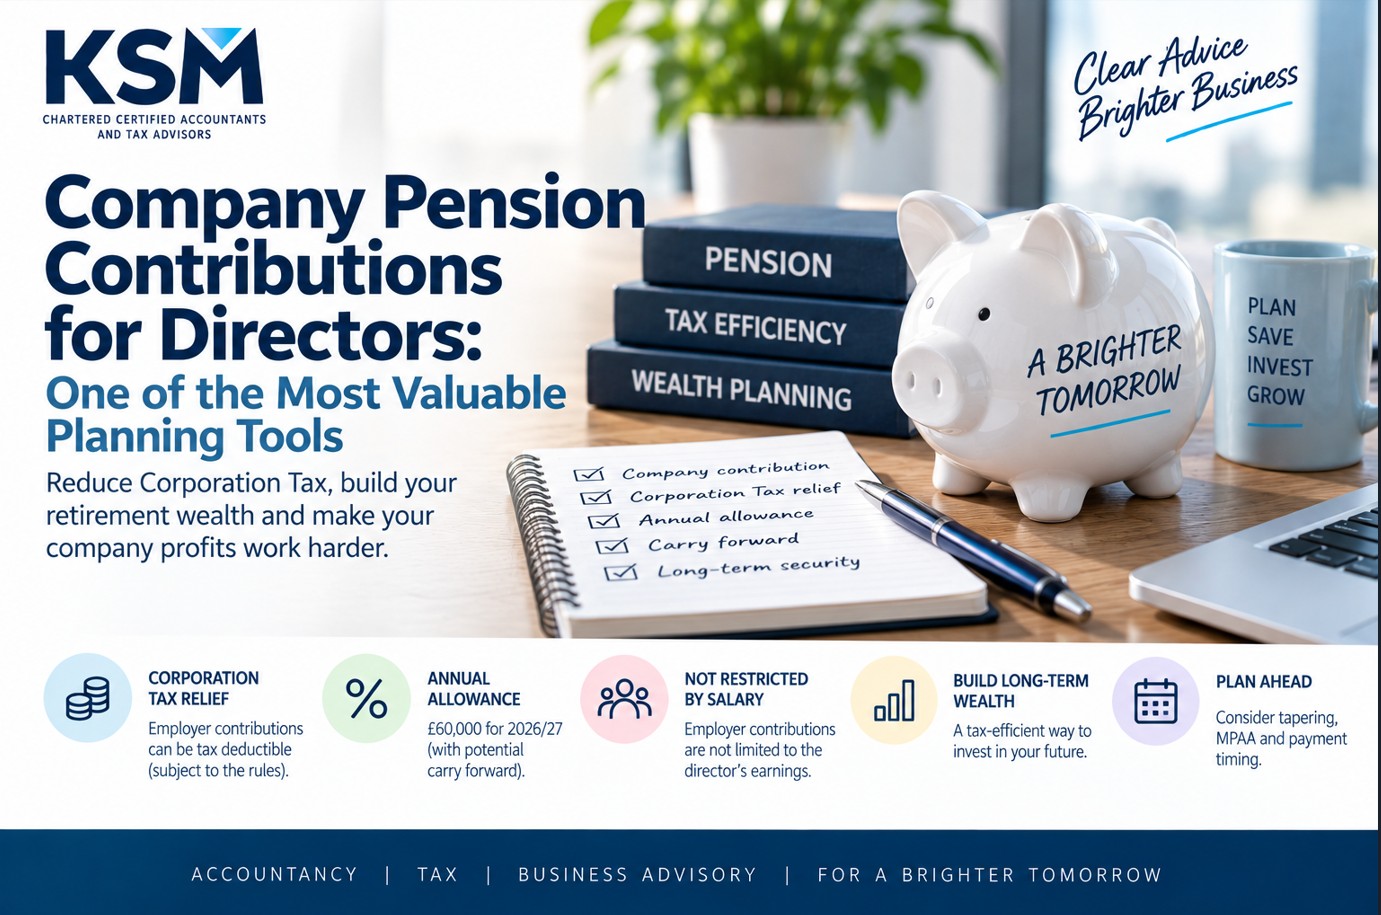
Each year, company pension contributions for directors can play a pivotal role in overall financial strategy.
A properly structured employer pension contribution can allow a company to move cash into a director’s pension without first paying that amount to the director as salary or dividend. Subject to the relevant conditions, the company may obtain Corporation Tax relief, while the contribution is generally not taxed on the director as employment income.
Understanding company pension contributions for directors is crucial for effective financial planning.
This can be particularly beneficial when considering company pension contributions for directors as a method of wealth accumulation.
For shareholder-directors who do not need to extract all available company profits for immediate personal spending, employer pension contributions can therefore be one of the most effective long-term profit extraction tools available.
Many directors overlook the advantages of company pension contributions for directors when planning their financial future.
However, the rules are not simply “the company can pay £60,000 tax-free”.
The annual allowance, carry forward, tapered annual allowance, money purchase annual allowance, Corporation Tax deductibility, contribution timing and the director’s wider pension history all need to be reviewed.
Why this matters
Owner-managed company directors commonly extract profits through a combination of:
Incorporating company pension contributions for directors in tax planning can lead to significant long-term benefits.
-
salary;
-
dividends;
Among these, company pension contributions for directors often provide the most substantial tax relief.
-
pension contributions;
-
repayment of money owed through a director’s loan account; and
-
other legitimate benefits and expenses.
Each method produces different tax consequences.
Understanding the implications of company pension contributions for directors is vital for optimal financial decisions.
Salary can generate Income Tax, employee National Insurance and employer National Insurance.
Dividends are paid from post-Corporation Tax profits and may then suffer dividend Income Tax personally.
An employer pension contribution works differently.
Ultimately, company pension contributions for directors can significantly impact personal tax efficiency.
This is where company pension contributions for directors can be particularly advantageous.
HMRC confirms that contributions made by an employer into a registered pension scheme for an employee are generally not treated as taxable earnings of that employee.
At company level, an employer contribution may also be deductible in calculating taxable trading profits where it satisfies the normal “wholly and exclusively” test. HMRC specifically states that pension contributions forming part of a remuneration package for a director or employee will generally be allowable where incurred wholly and exclusively for the purposes of the trade.
That combination can make pensions particularly valuable for directors building wealth for retirement.
Maximising company pension contributions for directors allows for enhanced retirement planning.
Employer contributions are different from personal contributions
This distinction is fundamental.
Directors should leverage company pension contributions for directors to make the most of available allowances.
Where an individual personally makes pension contributions, tax relief is subject to rules based partly on their relevant UK earnings.
For 2026/27, personal contributions eligible for tax relief are generally restricted by reference to the higher of £3,600 gross and 100% of relevant UK earnings, subject also to the pension tax rules.
Employer contributions do not work in the same way.
Those planning for retirement should actively consider company pension contributions for directors.
HMRC confirms that there is no equivalent fixed earnings-based ceiling on the amount for which an employer can potentially obtain relief. Instead, deductibility depends on the business-purpose rules, while the contribution still counts towards the director’s pension annual allowance.
This is particularly relevant to owner-directors who take a relatively modest salary.
A director earning, for example, £12,570 does not necessarily have to restrict their company’s employer pension contribution to £12,570.
That is one of the main differences between a personal pension contribution and a genuine employer contribution.
Awareness of company pension contributions for directors can lead to more informed financial planning.
The annual allowance for 2026/27
The standard pension annual allowance for the tax year 6 April 2026 to 5 April 2027 is £60,000.
The annual allowance considers total pension input across the individual’s relevant pension arrangements.
Company pension contributions for directors can significantly affect the overall financial strategy.
For a defined contribution pension, that can include:
-
personal contributions;
-
employer contributions; and
-
contributions by other parties.
Employer contributions are therefore not outside the annual allowance simply because the company pays them.
A director whose company contributes £60,000 and who has also personally contributed £10,000 during the same tax year could potentially have pension input of £70,000.
Whether this creates an annual allowance tax charge will depend on factors including available carry forward.
Utilising company pension contributions for directors effectively can enhance retirement savings.
Carry forward can substantially increase the available allowance
A particularly useful planning opportunity arises where the director has unused annual allowance from previous tax years.
For 2026/27, unused annual allowance can potentially be carried forward from:
-
2023/24;
-
2024/25; and
-
2025/26.
The individual must generally have been a member of a registered pension scheme in the relevant earlier tax year.
The current year’s annual allowance is used first, followed by unused allowance from previous years, starting with the earliest available year.
This can make considerably larger company pension contributions possible.
Strategies involving company pension contributions for directors are crucial for long-term success.
Example
Suppose a director has made no pension contributions during:
2023/24: £0
2024/25: £0
2025/26: £0
Assume throughout that the director had the full £60,000 annual allowance available and was a member of a registered pension scheme.
They could potentially have:
In this context, company pension contributions for directors should always be considered.
-
£60,000 current 2026/27 allowance;
-
£60,000 unused from 2023/24;
-
£60,000 unused from 2024/25; and
-
£60,000 unused from 2025/26.
That could give total available annual allowance of up to £240,000 in 2026/27.
Directors must understand the potential of company pension contributions for directors in enhancing their financial position.
This does not mean that every company should simply pay £240,000.
The company’s commercial position, wholly and exclusively test, previous pension input, scheme restrictions, tapering and the director’s wider circumstances must all be checked first.
Practical Example
Assume a profitable owner-managed trading company expects taxable profits of £400,000 before making a pension contribution for its director.
The director:
Incorporating company pension contributions for directors can lead to better financial outcomes.
-
is genuinely working full-time in the business;
-
has sufficient annual allowance;
-
has not triggered the money purchase annual allowance;
-
is not affected by the tapered annual allowance; and
-
has a registered pension scheme capable of receiving the contribution.
The company pays an employer pension contribution of £60,000 before its accounting year end.
These considerations make company pension contributions for directors an integral part of business strategy.
If the full £60,000 is deductible, taxable profits fall from:
£400,000 to £340,000.
At the 25% Corporation Tax main rate applying for the financial year beginning 1 April 2026, the Corporation Tax reduction would be:
£60,000 × 25% = £15,000
The company has therefore used £60,000 of cash to provide £60,000 of value within the director’s pension while potentially reducing Corporation Tax by £15,000. The director is not normally taxed on the £60,000 as salary merely because the company made the employer pension contribution.
By comparison, extracting £60,000 personally before investing it may first require salary or dividend taxation.
The comparison will vary depending on the director’s tax position, company profits, available allowances and future access requirements, but this demonstrates why pension contributions deserve consideration before remuneration decisions are finalised.
Corporation Tax relief is not automatic
A common misconception is that any pension contribution made by a company for its director automatically receives Corporation Tax relief.
These factors reinforce the importance of company pension contributions for directors in overall planning.
That is too simplistic.
The expense must satisfy the normal business-purpose test.
HMRC’s Business Income Manual states that employer contributions are allowable where they are incurred wholly and exclusively for the purposes of the trade. Pension contributions are normally viewed as part of the cost of employing staff, but HMRC can consider whether there is a non-trade purpose.
In summary, company pension contributions for directors offer unique benefits worth exploring.
For controlling directors, HMRC may consider the overall remuneration package.
A substantial pension contribution is not necessarily excessive merely because the recipient is a shareholder-director. The relevant question is whether the overall remuneration package is commercially justifiable for the work performed and the purposes of the business.
This becomes particularly important where contributions are being made for:
Ensuring clarity on company pension contributions for directors can prevent costly planning mistakes.
-
family members;
-
directors carrying out little work;
-
shareholders who are not employees; or
-
unusually large contributions bearing little relationship to the person’s role.
It is advisable to seek advice on company pension contributions for directors before making decisions.
The facts must support the treatment.
The contribution must actually be paid
Timing is another important planning point.
The Corporation Tax deduction for an employer contribution to a registered pension scheme is generally given in the accounting period in which the contribution is actually paid, rather than merely accrued in the accounts.
Suppose a company has a 31 December 2026 year end.
The directors decide on 20 December to contribute £50,000 to a pension but the payment does not reach the pension arrangement until January 2027.
Accounting entries made at 31 December do not necessarily produce Corporation Tax relief for the year ended 31 December 2026.
Therefore, company pension contributions for directors should be part of the regular review process.
This is why year-end pension planning should not be left until the final day.
The pension provider’s processing requirements and the date on which the contribution is treated as paid should be established in advance.
The tapered annual allowance
High-income directors need additional care.
For 2026/27, the tapered annual allowance can apply where both:
-
threshold income exceeds £200,000; and
Directors should regularly assess their approach to company pension contributions for directors.
-
adjusted income exceeds £260,000.
Where the taper applies, the £60,000 annual allowance is reduced by £1 for every £2 of adjusted income above £260,000, subject to a minimum tapered annual allowance of £10,000.
Crucially, employer pension contributions can themselves form part of adjusted income for this calculation.
Therefore, a large company pension contribution for a high-income director can affect the very annual allowance against which the contribution is tested.
This is an area where calculations should be performed before the payment is made.
Engaging with the topic of company pension contributions for directors can yield significant financial rewards.
The money purchase annual allowance
Directors who have already flexibly accessed a defined contribution pension may face another restriction.
For 2026/27, the Money Purchase Annual Allowance, or MPAA, is £10,000.
The MPAA can be triggered by certain types of flexible pension access.
Once triggered, it significantly restricts the tax-efficient amount that can subsequently be contributed to money purchase pension arrangements.
An important additional restriction is that unused MPAA itself cannot be carried forward.
This makes it essential to establish whether a director has already drawn pension benefits and, if so, exactly how those benefits were accessed.
In conclusion, company pension contributions for directors must be a focal point in financial discussions.
Simply asking whether the director has “taken their pension” is not sufficiently precise.
National Insurance advantages
A genuine employer contribution to a registered pension scheme is normally not treated in the same way as cash salary for employment tax purposes.
HMRC confirms that employer pension contributions qualifying under section 308 ITEPA 2003 are not charged on the employee as employment earnings.
This can make the comparison with additional salary particularly significant because salary can attract:
-
employee National Insurance;
-
employer National Insurance; and
-
PAYE Income Tax.
However, this does not mean a pension contribution should automatically replace salary.
The director may need cash for living costs, borrowing requirements or other commercial reasons, and salary can contribute towards National Insurance records and State Pension entitlement.
Pension planning therefore sits alongside remuneration planning rather than replacing it.
Common pitfalls
1. Assuming the £60,000 allowance is an employer contribution limit
It is an annual allowance applying to the individual’s overall pension input. Carry forward can increase the available amount, while tapering or the MPAA can reduce it.
2. Restricting employer contributions to the director’s salary
The relevant UK earnings restriction applicable to tax relief on personal contributions does not operate in the same way for genuine employer contributions.
3. Ignoring previous pension contributions
The annual allowance applies across relevant pension arrangements, not just the pension into which the company proposes to contribute.
4. Missing the accounting year-end deadline
Corporation Tax relief is generally based on when the employer contribution is paid. An accrual alone is normally insufficient.
5. Forgetting about the tapered annual allowance
Large employer contributions can increase adjusted income and may reduce the annual allowance available to a high-income director.
6. Ignoring previous flexible pension withdrawals
A director who has triggered the MPAA may have only £10,000 of money purchase annual allowance rather than the standard £60,000.
Tax planning and commercial opportunities
Employer pension contributions are particularly worth considering where a company:
-
has surplus cash beyond its working capital requirements;
-
is consistently profitable;
-
has directors who do not need to extract all profits immediately;
-
expects the director to build retirement funds over several years;
-
has unused annual allowance potentially available through carry forward; or
-
is undertaking year-end Corporation Tax planning.
They can also form part of a broader comparison between salary, dividends, pension funding and retained profits.
The correct answer is not always to maximise pension contributions.
Once money enters a pension, access is restricted by pension legislation and scheme rules. A director who may need the funds to purchase a home, support another investment or fund personal expenditure should not regard pension contributions as equivalent to cash extraction.
Tax efficiency should not override liquidity planning.
Action points for business owners
Before making a significant company pension contribution, directors should establish:
-
the director’s total pension input for 2026/27;
-
pension contributions made during the previous three tax years;
-
whether unused annual allowance can be carried forward;
-
whether the tapered annual allowance applies;
-
whether the MPAA has been triggered;
-
whether the pension scheme can accept the proposed employer contribution;
-
whether the contribution is commercially supportable as part of the director’s remuneration;
-
the company’s expected Corporation Tax position;
-
the company’s working-capital requirements after making the payment; and
-
whether the contribution will actually be paid before the company’s intended accounting deadline.
KSM perspective
For many profitable owner-managed companies, employer pension contributions should be considered before deciding how all available profits will be extracted.
The attraction is straightforward.
Subject to the rules, the company can transfer value directly into the director’s pension, potentially obtain Corporation Tax relief and avoid treating the contribution as ordinary salary or dividend income at the point of payment.
For 2026/27, the standard £60,000 annual allowance, combined with the possibility of using unused allowance from the previous three tax years, can provide substantial planning capacity.
But pension planning is not simply a matter of paying £60,000 before the year end.
A robust review needs to consider the company’s taxable profits, Corporation Tax rate, the director’s previous pension history, tapering, flexible access, cash requirements and whether the overall remuneration package satisfies the business-purpose test.
The best time to undertake that review is before the company year end and before dividends or other extraction decisions have exhausted the available cash.
Tax and accounting treatment will depend on the particular circumstances of the company and its shareholders or directors. Pension rules and available allowances will also depend on the individual’s pension history and circumstances. This article provides general information only and should not be treated as personalised tax, accounting, pension, investment or legal advice. Appropriate professional advice should be obtained before implementing any transaction or planning strategy.
This article is general guidance only and does not constitute tailored tax advice. Please contact KSM Consulting Ltd for advice based on your circumstances.